Updated November 2026. Is a rental property worth buying? This free return on investment (ROI) calculator shows the four numbers UK landlords use to judge a deal: gross yield, net yield, annual cash flow and cash-on-cash ROI. Enter your own figures; the defaults show a typical £150,000 buy-to-let bought with a 75% interest-only mortgage.
Rental property ROI calculator
Results update as you type. All figures are before income tax.
Key takeaways
- Gross yield compares properties quickly; net yield shows what is left after running costs.
- Cash-on-cash ROI measures the return on the money you actually put in, after mortgage interest.
- Count every pound of cash invested: deposit, stamp duty, legal fees and refurbishment.
- Tax matters: from April 2027 rental profits are due to be taxed at 24%, 44% or 49%, which can cut an after-tax ROI by more than half.
The four formulas behind the calculator
Gross yield
annual rent ÷ price × 100
A quick headline figure for comparing listings.
Net yield
(rent − running costs) ÷ price × 100
What the property earns before finance.
Annual cash flow
rent − costs − mortgage interest
Money left each year, before tax.
Cash-on-cash ROI
cash flow ÷ cash invested × 100
The return on your own money.
Worked example: a £150,000 buy-to-let
These are the calculator's default figures. The buyer puts down a 25% deposit (£37,500), pays £8,000 stamp duty with the 5% surcharge (check it with our buy-to-let stamp duty calculator) and about £1,500 in fees, so £47,000 of cash goes in. The £112,500 interest-only mortgage at 5% costs about £470 a month.
| Item | Annual figure |
|---|---|
| Rent (£1,100 a month) | £13,200 |
| Running costs (£250 a month) | −£3,000 |
| Mortgage interest (£470 a month) | −£5,640 |
| Cash flow before tax | £4,560 |
| Gross yield | 8.8% |
| Net yield | 6.8% |
| Cash-on-cash ROI before tax | 9.7% |
What to include in each figure
Running costs
Use real quotes where you can. Typical lines are letting or management fees, landlord insurance, repairs and maintenance, ground rent and service charge for flats, safety certificates, licensing fees, and an allowance for empty periods between tenants. Our list of 15 hidden buy-to-let costs is a good checklist. Under-counting costs is the most common reason a deal looks better on paper than in practice.
Mortgage interest
Enter the interest only, not capital repayments. Capital repayment builds your equity rather than being a cost, so it belongs in a separate cash-flow check. Use the rate you will pay after any fixed deal ends, not just the introductory rate.
Cash invested
Everything that left your bank account to get the property let: deposit, stamp duty, legal and survey fees, mortgage arrangement fees, broker fees and any refurbishment. Leaving out stamp duty alone can overstate ROI by a fifth.
How tax changes your ROI
The calculator shows returns before income tax, because tax depends on your other income. It matters a lot. Following the Autumn Budgets of 2025 and 2026, rental profits for individual landlords in England, Wales and Northern Ireland are due to be taxed at separate property rates of 24%, 44% and 49% from 6 April 2027. Mortgage interest is not deducted as an expense; instead you get a tax credit, expected to follow the new property basic rate.
For a higher-rate landlord, the example above works out roughly like this from April 2027: tax of 44% on £10,200 (rent less running costs) is £4,488, less a credit of about £1,354 for the interest, leaving around £3,134 to pay. After-tax cash flow falls to about £1,426 and the cash-on-cash ROI to about 3%. Read our Budget 2026 landlord tax guide for the detail.
| Tax | Rate (England) | Effect on ROI |
|---|---|---|
| Stamp duty on purchase | Standard bands plus 5% for additional homes | Raises cash invested |
| Income tax on rental profit | 20%, 40%, 45% now; 24%, 44%, 49% from April 2027 | Reduces annual return |
| Capital gains tax on sale | 18% or 24% (2026/27) | Reduces the gain when you sell |
| Corporation tax (company landlords) | 19% to 25% | Applies instead of income tax |
Holding property in a company changes the maths but brings its own costs, including stamp duty and CGT if you move existing properties in. See our limited company buy-to-let guide.
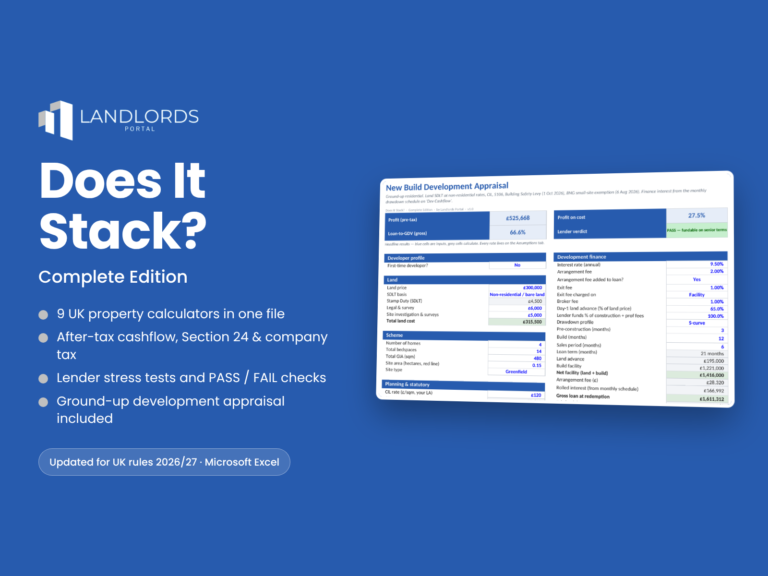
Excel deal calculator
Go beyond a simple ROI figure
Does It Stack? works out cash flow, yield and return on cash for UK deals after stamp duty, finance costs, Section 24 and lender stress tests.
- Buy to let, HMO, BRR, flip, rent-to-rent, holiday let and development tabs
- UK stamp duty surcharges, Section 24 and lender stress tests built in
- A clear answer: does the deal stack or not?
What is a good ROI on a rental property?
There is no single right answer: it depends on your risk appetite, the area and how much capital growth you expect. As a rule of thumb, compare the after-tax cash-on-cash ROI with what the same cash would earn risk-free in savings, then ask whether the extra work, risk and illiquidity are worth the difference. Higher-yield strategies such as HMOs usually pay more but cost more to run and regulate; test them with our HMO deal calculator. For ways to lift a weak return, see how to increase your rental yield.
Common ROI mistakes
- Using the asking rent. Check what similar homes actually let for, not what agents advertise.
- Forgetting voids and repairs. A month empty each year costs over 8% of the rent.
- Leaving stamp duty out of cash invested. It is a real cost and you cannot claim it against rent.
- Testing only today's mortgage rate. Re-run the numbers at 1 to 2 percentage points higher.
- Ignoring tax. A pre-tax ROI can look healthy while the after-tax return is thin.
- Counting expected house price growth as income. Growth is not guaranteed and is only realised when you sell, after CGT.
Frequently asked questions
How do you calculate ROI on a rental property?
Take the annual rent, subtract running costs and mortgage interest to get cash flow, then divide by the total cash you invested and multiply by 100.
What is the difference between yield and ROI?
Yield compares income with the property's price. ROI compares your profit with the cash you put in, so it reflects the effect of a mortgage.
Should I include capital growth in ROI?
Keep it separate. Judge the income return on its own, then treat growth as a possible bonus that is taxed when you sell.
How do mortgage rates affect ROI?
Directly. On a £112,500 interest-only loan, each 1 percentage point rise adds £1,125 a year in interest, which cuts the example's pre-tax ROI from 9.7% to about 7.3%.
Does the calculator include tax?
No. It shows pre-tax returns because tax depends on your income and ownership structure. Use the tax section above to estimate the after-tax figure.
Written by The Landlords Portal Team. Tax rates checked against Budget 2026 announcements in November 2026; the April 2027 property rates are subject to legislation. General information, not financial or tax advice.
Excel calculator from Landlords Portal
Does the deal stack after tax?
The Does It Stack? calculator shows your cashflow after stamp duty, Section 24 and running costs, and whether a lender will pass the deal.
- Buy-to-let, BRR, HMO, flips, holiday lets and development in one Excel file
- Cashflow after stamp duty, Section 24 and running costs
- Lender stress test before you make an offer